
Nigeria has often been regarded as the "gateway to Africa", but its push to become a gateway for African cross-border payments faces a deeper infrastructure challenge than its fintech apps suggest.
As fintechs expand regionally, the challenge is increasingly shifting to the infrastructure behind these transactions.
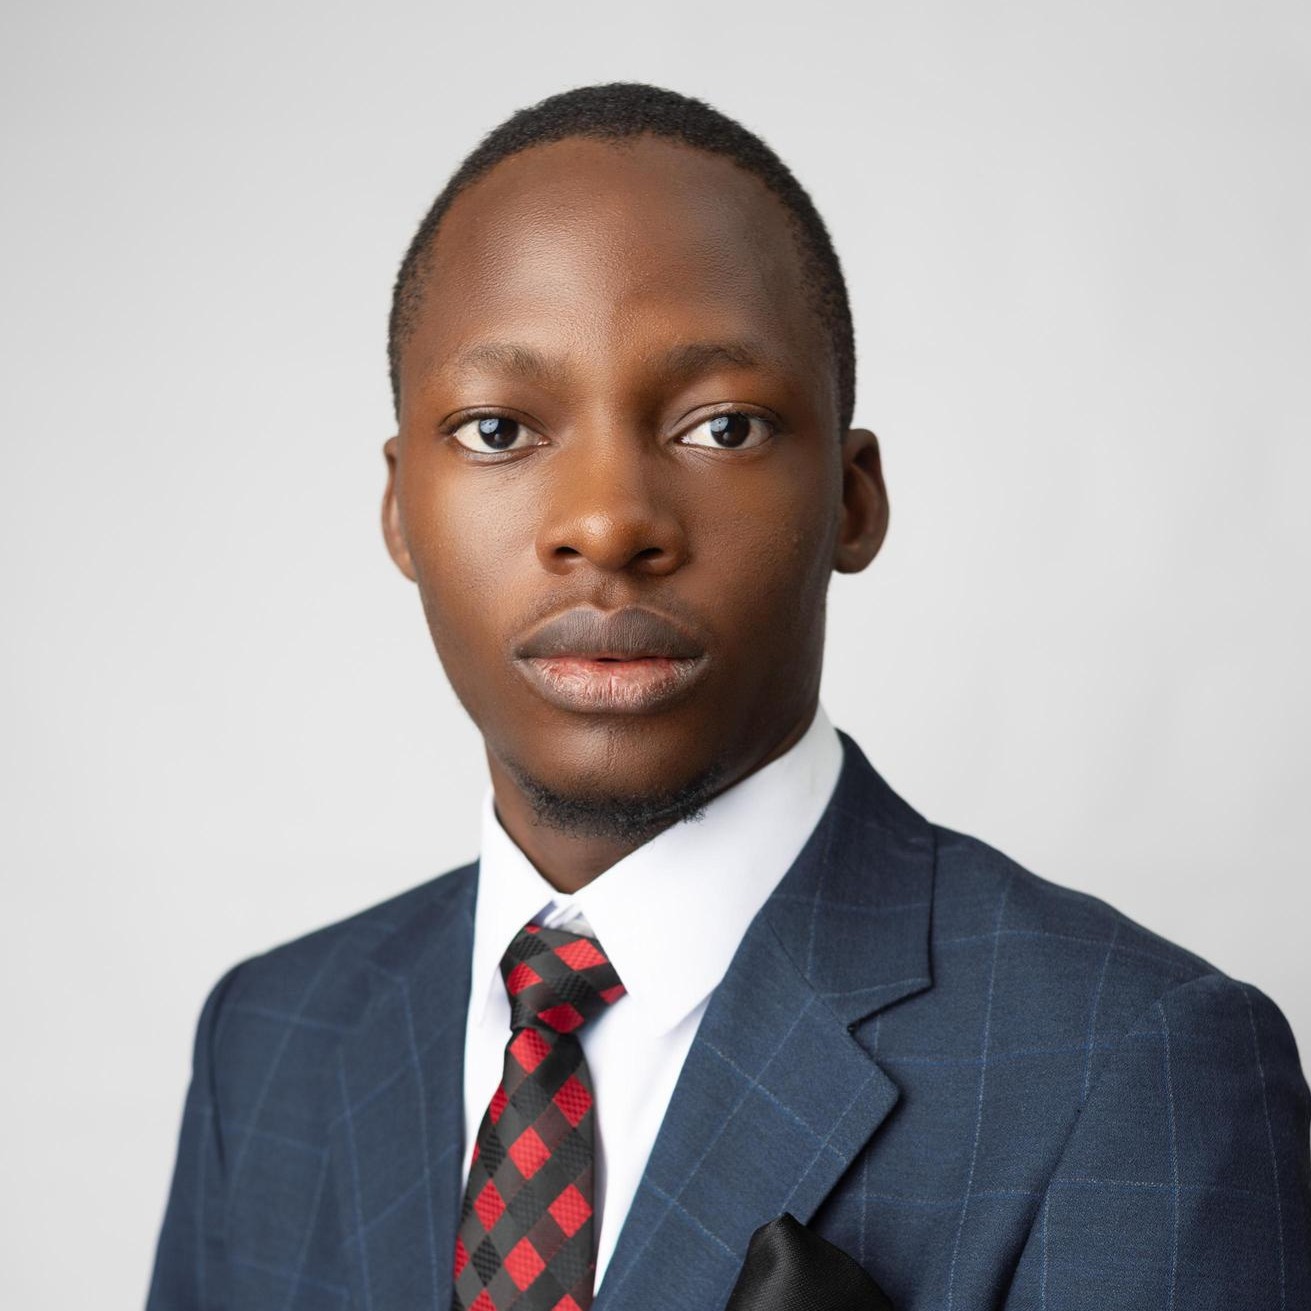
In an exclusive interview with ITWeb Africa, Rustam Bagautdinov, director of processing at Payzon, said Nigerian fintechs have built strong domestic payment experiences, but cross-border transactions remain constrained by fragmented clearing systems, FX liquidity and regulatory differences.
He said Nigeria's domestic instant-payment ecosystem benefits from operating within a single-currency environment, while transactions with Ghana, Kenya and the West African Economic and Monetary Union often require fintechs to maintain prefunded accounts with partner banks.
"The conversation around Nigerian fintechs spearheading Africa's cross-border financial integration often suffers from a fundamental misconception: confusing consumer-facing app velocity with actual backend settlement," Bagautdinov said.
According to him, this model can make transfers appear instant while leaving providers to manage working capital, FX exposure and reconciliation.
He said the challenge becomes more significant for business-to-business payments, merchant acquiring and supply-chain finance, where high volumes and tighter margins make inefficient settlement costly.
The comments come as cross-border payment infrastructure expands rapidly across Africa.
The Pan-African Payment and Settlement System (PAPSS) said in July that its network had grown to 28 countries, more than 190 commercial banks and fintechs, and 16 switches, following the entry of the Bank of Central African States.
By September, PAPSS said it had expanded further still, to more than 30 countries, 24 national and regional central banks, and over 200 commercial banks and payment service providers.
PAPSS chief executive Mike Ogbalu III has described the platform's expansion as part of efforts to make intra-African payments more seamless, while Afreximbank says the system can reduce reliance on foreign currencies in trade.
Bagautdinov said Nigeria's emergence as a regional gateway would require integration between domestic switches and continental settlement infrastructure, alongside intraday FX liquidity management and harmonised technical protocols.
He pointed to ISO 20022 messaging, switch interoperability and consistent security standards as components of a scalable regional payments architecture.
Bagautdinov said Nigeria's opportunity lies beyond faster payment applications, urging fintechs to focus on the underlying mechanics of cross-border clearing, switch interoperability and real-time liquidity.
Share